Does Your State Tax Your HSA? California and New Jersey Are Different
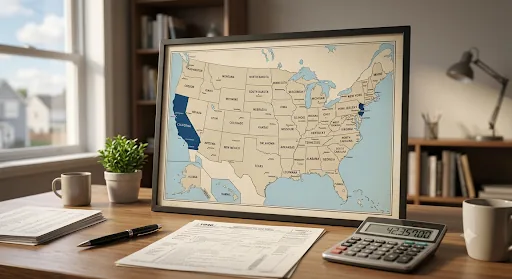
HSAs get their federal tax break — pre-tax contributions, tax-free growth, tax-free qualified withdrawals — automatically in nearly every state. California and New Jersey are the exception, and the gap is bigger than most residents realize until tax season.
Key takeaways
- California and New Jersey are the only two states that don't conform to federal HSA tax treatment.
- It's not just contributions — investment growth inside the HSA is taxed annually in these two states too.
- The federal advantage still applies regardless of state; this is a real cost to know about, not a reason to skip an HSA.
What's different in these two states
Both states decline to conform to the federal tax treatment of HSAs. In practice that means three separate things, not just one: contributions aren't deductible on the state return, investment growth inside the HSA is taxed annually as it's earned (interest, dividends, and realized capital gains), and even qualified withdrawals can carry state tax consequences depending on how the state tracks your basis in the account.
What this looks like on a paycheck
If you contribute through payroll, the mechanics are simple even if the outcome is annoying: your HSA contribution is excluded from federal taxable wages but added back into state taxable wages, and it shows up as state-taxable income on your W-2. Employer contributions get the same treatment — money your employer puts into your HSA is federally tax-free to you but counted as state taxable income in California and New Jersey.
The part people miss: it's not just contributions
Because these states don't treat the HSA as tax-sheltered at all, they also tax whatever the account earns while it sits invested — the way a regular brokerage account works, not a retirement account. A federally tax-free HSA used as a long-term investment vehicle (the "shoebox strategy" described in our reimbursement guide) loses more of its advantage in these two states than a simple pre-tax-contribution comparison would suggest, since the growth itself is taxed every year it's earned, not just the contribution.
Does this change whether you should use an HSA?
Usually not by itself. You still get the full federal advantage — pre-tax contributions and tax-free qualified withdrawals at the federal level — regardless of which state you live in. The state-level gap is a real cost, particularly for anyone investing HSA funds for growth over many years, but for most people it doesn't outweigh the federal benefit; it's a factor to know about, not a reason to opt out.
Sources: California Franchise Tax Board and New Jersey Division of Taxation guidance on HSA non-conformity. This is general information, not state-specific tax advice — confirm your own situation with a tax professional licensed in your state.
Your next step
Learn what applies to you, run your own numbers, then act on it.